Child Tax Credit 2026: Expanded Benefits & Eligibility Guide
Anúncios
As we look ahead to the financial landscape of 2026, one of the most significant considerations for American families is the future of the Child Tax Credit (CTC). This vital federal tax benefit has been a cornerstone of support for millions of households, helping to alleviate the costs associated with raising children. With potential expansions and adjustments on the horizon, understanding the nuances of the Child Tax Credit 2026 is paramount for maximizing your family’s financial well-being.
The CTC has a rich history of evolution, adapting to the economic needs of the nation. For 2026, discussions and proposals often center around making some of the more generous provisions from previous years permanent or introducing new enhancements. These changes could significantly impact eligibility, the maximum credit amount, and how families receive these crucial funds. This comprehensive guide will delve into the anticipated structure of the Child Tax Credit 2026, examining potential income thresholds, eligibility criteria, and the steps you’ll need to take to claim up to $3,600 per child.
Whether you’re a first-time parent, managing a growing family, or simply planning for your financial future, staying informed about the Child Tax Credit 2026 is essential. We will break down complex tax language into understandable terms, providing actionable insights to ensure you are well-prepared to take full advantage of this important benefit. From understanding the definition of a ‘qualifying child’ to navigating the intricacies of income limitations, this article aims to be your definitive resource.
Anúncios
Understanding the Child Tax Credit: A Brief History and Future Outlook
The Child Tax Credit was first introduced in 1997 as a non-refundable credit to help offset the costs of raising children. Over the years, it has undergone several significant modifications, most notably with the Tax Cuts and Jobs Act (TCJA) of 2017, which increased the maximum credit to $2,000 per qualifying child, made up to $1,400 refundable, and raised income thresholds. However, the most substantial, albeit temporary, expansion occurred with the American Rescue Plan Act (ARPA) of 2021.
Under ARPA, the CTC was significantly enhanced for 2021, increasing to $3,600 for children under age six and $3,000 for children aged six to seventeen. Crucially, it also made the credit fully refundable for many families and allowed for advance monthly payments. While these provisions expired after 2021, the impact was profound, lifting millions of children out of poverty and demonstrating the potential of a more generous and accessible credit.
The discussion surrounding the Child Tax Credit 2026 often revolves around whether to reinstate or modify these ARPA-era enhancements. Lawmakers from both sides of the aisle recognize the importance of the CTC, but differing views on its structure, refundability, and income phase-outs often lead to complex negotiations. For 2026, families can expect a credit that, at minimum, resembles the TCJA-era structure, but there is significant political will and ongoing debate to push for a more expansive version. The core objective remains to provide financial relief to families, stimulate economic growth, and support child well-being.
Who is a Qualifying Child for the Child Tax Credit 2026?
To claim the Child Tax Credit 2026, understanding the definition of a ‘qualifying child’ is fundamental. The IRS has specific criteria that a child must meet for you to claim them for the credit. These criteria are generally consistent across different iterations of the CTC, though age limits and residency requirements can sometimes see minor adjustments.
Anúncios
Typically, for a child to be considered a qualifying child for the CTC, they must meet all of the following tests:
- Age Test: The child must be under a certain age at the end of the tax year. For the standard CTC, this is usually age 17 (meaning they are 16 or younger). If ARPA-like provisions are reinstated, this could extend to age 17, and the credit amount might differentiate between younger and older children.
- Relationship Test: The child must be your son, daughter, stepchild, foster child, brother, sister, half-brother, half-sister, stepbrother, stepsister, or a descendant of any of them (for example, a grandchild, niece, or nephew).
- Residency Test: The child must have lived with you for more than half of the tax year. There are exceptions for temporary absences, such as for schooling, medical treatment, or military service.
- Support Test: The child must not have provided more than half of their own support for the year.
- Joint Return Test: If the child is married, they cannot file a joint return for the year (unless they file it only to claim a refund of withheld income tax or estimated tax paid).
- Citizenship Test: The child must be a U.S. citizen, U.S. national, or U.S. resident alien.
It’s crucial to verify these specific requirements as they are finalized for the Child Tax Credit 2026, as even minor changes can affect eligibility. Keeping accurate records of your child’s age, residency, and support throughout the year will be vital when tax season arrives.
Navigating the New Income Thresholds for 2026
One of the most critical aspects of the Child Tax Credit 2026, and often the subject of legislative debate, is the income threshold. These thresholds determine whether your family qualifies for the full credit, a partial credit, or no credit at all. Historically, the CTC has included both phase-in and phase-out rules based on a taxpayer’s Modified Adjusted Gross Income (MAGI).
Standard Income Phase-Outs (Pre-ARPA Baseline)
Prior to the ARPA expansion, the CTC began to phase out for higher-income taxpayers. For example, under the TCJA, the credit started to reduce by $50 for every $1,000 by which a taxpayer’s MAGI exceeded:
- $200,000 for single filers and heads of household.
- $400,000 for married couples filing jointly.
These thresholds are significantly higher than the phase-out thresholds that applied to the ARPA-enhanced credit. If no new legislation is passed, the Child Tax Credit 2026 will likely revert to these higher phase-out thresholds, making the full credit available to a broader range of middle and upper-middle-income families.
Potential ARPA-Era Income Thresholds (If Reinstated)
If Congress decides to reinstate or modify ARPA-like provisions for the Child Tax Credit 2026, families could see a different set of income thresholds. The ARPA expansion introduced two tiers of phase-outs:
- The first tier reduced the expanded portion of the credit ($1,600 or $1,000, depending on the child’s age) for MAGI above:
- $75,000 for single filers.
- $112,500 for heads of household.
- $150,000 for married couples filing jointly.
- Once the expanded portion was phased out, the remaining $2,000 per child credit would then begin to phase out at the higher thresholds mentioned above ($200,000 for single, $400,000 for married filing jointly).
These lower initial phase-out thresholds meant that while more families at the lower end of the income spectrum received the full credit, some middle-income families saw their credit reduced sooner than under the TCJA rules. The political debate for the Child Tax Credit 2026 will heavily hinge on which set of income thresholds, or a hybrid approach, is ultimately adopted.
Families should closely monitor legislative developments regarding the Child Tax Credit 2026 to understand which income thresholds will apply to their specific filing status and income level. Using the IRS’s online tools or consulting with a tax professional once the final rules are established will be crucial for accurate planning.
The Maximum Benefit: Claiming Up to $3,600 Per Child
The possibility of claiming up to $3,600 per child for the Child Tax Credit 2026 is a significant draw for many families. This maximum amount was a hallmark of the 2021 expansion and, if reinstated, would provide substantial financial relief. However, achieving this maximum benefit depends on several factors, including the child’s age, your income, and the overall structure of the credit as legislated for 2026.
Age-Based Variations
If the ARPA-era structure is adopted for the Child Tax Credit 2026, the maximum credit amount would likely be:
- $3,600 per child for qualifying children who are under age six at the end of the tax year.
- $3,000 per child for qualifying children who are between ages six and seventeen (inclusive) at the end of the tax year.
If the CTC reverts to its pre-ARPA structure, the maximum credit would be $2,000 per qualifying child under age 17, with no differentiation based on age within that range. The ongoing legislative discussions will determine which of these structures, or a modified version, will apply to the Child Tax Credit 2026.
Refundability and the Maximum Benefit
Another key factor in realizing the maximum benefit is the credit’s refundability. A refundable credit means that if the credit amount exceeds your tax liability, you can receive the difference as a refund. The ARPA expansion made the CTC fully refundable for many families, which was particularly impactful for low-income households with little to no tax liability.
Under the pre-ARPA rules, only up to $1,400 of the $2,000 credit was refundable (known as the Additional Child Tax Credit, or ACTC), and it was subject to an earnings test. For the Child Tax Credit 2026, the extent of refundability will significantly influence how many families can access the full potential benefit, especially those with lower incomes. A fully refundable credit ensures that the benefit reaches those who need it most, regardless of their tax burden.
Families aiming to claim the maximum $3,600 (or $3,000) per child must ensure they meet all eligibility criteria, including the income thresholds applicable to the Child Tax Credit 2026. Accurate reporting of income and dependents on your tax return is crucial.
How to Claim the Child Tax Credit 2026
Claiming the Child Tax Credit 2026 will typically involve filing a federal income tax return. While the specific forms and schedules might vary slightly depending on the final legislation, the general process remains consistent.
Filing Your Tax Return
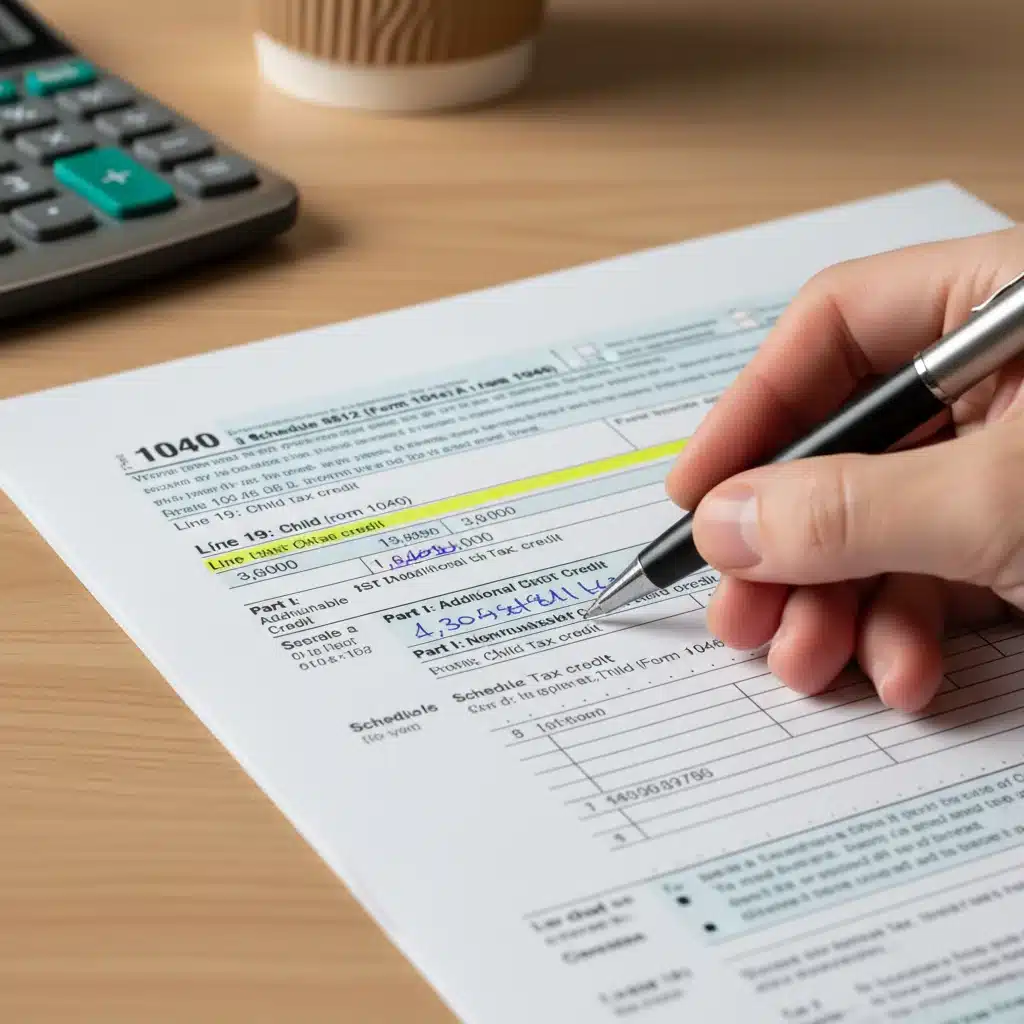
Most taxpayers will claim the CTC by completing IRS Form 1040, U.S. Individual Income Tax Return, and attaching Schedule 8812, Credits for Qualifying Children and Other Dependents. This schedule is where you’ll list your qualifying children and calculate the amount of your credit. It’s essential to follow the instructions carefully to ensure you claim the correct amount.
Required Information and Documentation
When preparing to claim the Child Tax Credit 2026, you’ll need to have the following information readily available:
- Social Security Number (SSN) for each qualifying child: This is a mandatory requirement for the CTC. Without a valid SSN for each child, you cannot claim the credit for them.
- Proof of relationship: Birth certificates, adoption papers, or other legal documents may be needed if the IRS requests verification.
- Proof of residency: School records, medical records, or other documents showing the child lived with you for more than half the year.
- Income documentation: W-2s, 1099s, and other income statements to accurately calculate your MAGI.
Keeping thorough records throughout the year can simplify the tax filing process and provide necessary documentation if your return is selected for review by the IRS.
Advance Payments (If Reinstated)
One of the most impactful features of the ARPA expansion was the provision for advance monthly payments of the CTC. If similar provisions are reinstated for the Child Tax Credit 2026, eligible families could receive a portion of their estimated credit amount in regular installments throughout the year, rather than waiting until tax filing season. This provides a more consistent financial buffer for families.
If advance payments are an option, the IRS would likely provide an online portal for families to manage their payments, update their information, or opt out if they prefer to receive the full credit at tax time. Monitoring IRS announcements as 2026 approaches will be vital for understanding if this feature returns.
Impact on Lower and Middle-Income Families
The design of the Child Tax Credit 2026 will have a profound impact on families across various income brackets, particularly those in lower and middle-income categories. The discussions around refundability and income thresholds are central to how effectively the credit supports these households.
Boosting Low-Income Households
For low-income families, a fully refundable CTC is transformative. Without a refundability clause, families with little to no tax liability cannot receive the full benefit of the credit, often missing out on a significant portion of the intended support. The ARPA expansion, by making the credit fully refundable, dramatically reduced child poverty rates. If the Child Tax Credit 2026 includes full refundability, it will continue to serve as a crucial lifeline for families struggling to meet basic needs, providing funds for food, housing, childcare, and other essentials. This direct financial injection helps stabilize households and improve child outcomes.
Supporting Middle-Income Families
Middle-income families also stand to benefit significantly from the Child Tax Credit 2026, especially if the higher income phase-out thresholds (such as $200,000 for single filers and $400,000 for married couples filing jointly) are retained. These thresholds ensure that a broad range of working families can qualify for the full or a substantial portion of the credit, helping to offset the rising costs of childcare, education, and daily living. For many middle-income families, the CTC can mean the difference between struggling to save and being able to invest in their children’s future, whether through educational opportunities or extracurricular activities.
The specific income thresholds and phase-out rates will dictate the exact level of support middle-income families receive. A more generous phase-out structure would allow more families to retain a larger portion of the credit, providing a wider economic benefit. The ongoing legislative debate aims to strike a balance that provides meaningful support without unduly burdening the federal budget.
The Economic and Social Impact of an Expanded CTC
Beyond individual family budgets, the structure of the Child Tax Credit 2026 has broader economic and social implications. A robust and expanded CTC can serve as a powerful tool for economic stimulus and social equity.
Economic Stimulus
When families receive additional funds through the CTC, they often spend it on essential goods and services. This increased consumer spending injects money directly into local economies, supporting businesses and jobs. Studies on the ARPA expansion showed a measurable boost in economic activity due to the increased purchasing power of families. If the Child Tax Credit 2026 maintains or expands upon these benefits, it could contribute to sustained economic growth, particularly in communities where families are most reliant on such support.
Poverty Reduction and Child Well-being
Perhaps the most significant social impact of an expanded CTC is its proven ability to reduce child poverty. The 2021 expansion demonstrated that a more generous and fully refundable credit can lift millions of children out of poverty, significantly improving their living conditions and future prospects. Access to better nutrition, healthcare, and educational resources can have long-term positive effects on a child’s development and their ability to thrive.
Moreover, the stability provided by the CTC can reduce parental stress, leading to a healthier family environment. By investing in children through robust tax credits, society invests in its future workforce and citizenry, fostering greater equity and opportunity across generations. The debate surrounding the Child Tax Credit 2026 is not just about tax policy; it’s about the kind of society we want to build for our children.
Common Questions and Misconceptions about the Child Tax Credit 2026
As discussions about the Child Tax Credit 2026 continue, several common questions and misconceptions often arise. Addressing these can help families better prepare.
Will the Child Tax Credit be permanent?
While there is strong bipartisan support for the CTC in some form, the permanence of the ARPA-era enhancements (like full refundability and higher credit amounts) is subject to ongoing legislative negotiation. As of now, it’s not permanently expanded, but efforts are continually made to make it so. The Child Tax Credit 2026 will reflect the outcome of these legislative efforts.
Do I need to pay back the Child Tax Credit?
Generally, no. The Child Tax Credit is a credit, not a loan. If you received advance payments in 2021, and your eligibility changed (e.g., your income increased significantly, or a child moved out), you might have had to repay some or all of the excess advance payments. However, for credits claimed at tax time, you do not ‘pay back’ the credit unless there was an error in calculation or fraud. It reduces your tax liability dollar for dollar, and if refundable, can result in a refund.
What if my child turns 17 during 2026?
For the standard (pre-ARPA) CTC, a child must be under 17 at the end of the tax year. This means if your child turns 17 on December 31, 2026, they would not qualify for the CTC for that year. If they turn 17 on January 1, 2027, they would qualify for 2026. If ARPA-like provisions are reinstated that allow 17-year-olds to qualify, then this would change, and they would be eligible for the $3,000 credit. Always check the final legislation for the Child Tax Credit 2026.
Does the Child Tax Credit affect other benefits?
The Child Tax Credit is a federal tax benefit and generally does not directly impact eligibility for other federal means-tested benefits like SNAP or Medicaid. However, if you receive a large tax refund due to the CTC, and you hold onto those funds, they could potentially count towards asset limits for certain programs. It’s always best to consult with a benefits specialist if you have concerns about specific programs.
Preparing for the Child Tax Credit 2026
To ensure you’re fully prepared to claim the Child Tax Credit 2026, proactive steps throughout the year can make a significant difference:
- Stay Informed: Keep an eye on legislative updates from Congress and announcements from the IRS regarding the CTC. Official IRS publications and reputable tax news sources will be your best guides.
- Maintain Accurate Records: Document all relevant information for your qualifying children, including their SSNs, birth dates, and residency details. Keep records of your income and any significant life changes.
- Estimate Your Income: If you anticipate significant changes to your household income in 2026, consider how this might affect your eligibility for the CTC, especially concerning phase-out thresholds.
- Consult a Tax Professional: For complex situations or if you have specific questions about your eligibility, a qualified tax professional can provide personalized advice and ensure you claim all the credits you are entitled to.
- Utilize IRS Resources: The IRS website offers a wealth of information, FAQs, and sometimes even interactive tools to help taxpayers understand and calculate their credits.
The Child Tax Credit 2026 represents a crucial opportunity for families to receive financial assistance. By understanding the potential changes, eligibility requirements, and claiming process, you can confidently navigate the tax landscape and ensure your family benefits from this vital support.
Conclusion
The Child Tax Credit 2026 stands as a beacon of financial support for American families, offering a significant opportunity to offset the considerable costs of raising children. While the exact parameters of the credit for 2026 are still subject to legislative finalization, the discussions primarily revolve around the potential reinstatement of enhanced benefits, including higher credit amounts (up to $3,600 per child) and expanded refundability, reminiscent of the impactful 2021 provisions. Families should prepare for a credit that, at minimum, provides $2,000 per qualifying child, but with a strong possibility of more generous terms.
Key takeaways for families include the critical importance of understanding the definition of a ‘qualifying child’—meeting age, relationship, residency, support, and citizenship tests. Furthermore, navigating the income thresholds will be paramount, as these determine whether you qualify for the full, partial, or no credit. Staying abreast of legislative developments will inform whether the more inclusive ARPA-era income limits or the higher pre-ARPA thresholds will apply, significantly impacting eligibility for middle and upper-middle-income households.
Claiming the Child Tax Credit 2026 will typically involve filing IRS Form 1040 and Schedule 8812, backed by accurate documentation of your children’s Social Security Numbers and residency. The potential return of advance monthly payments could also offer timely financial relief throughout the year, rather than a lump sum at tax time. The broader economic and social benefits of a robust CTC, including poverty reduction and economic stimulus, underscore its importance not just for individual families but for the nation as a whole.
As 2026 approaches, proactive engagement—staying informed, maintaining meticulous records, and consulting with tax professionals when necessary—will empower families to confidently claim the maximum benefit they are entitled to. The Child Tax Credit 2026 is more than just a line on a tax form; it’s an investment in the future of our children and the financial stability of countless homes across America.