Special Investigation: Unforeseen Impact of January 2026 Interest Rate Hike on Small Businesses
Anúncios
Special Investigation: The Unforeseen Impact of the January 2026 Interest Rate Hike on Small Businesses
The economic landscape is a constantly shifting terrain, and for small businesses, understanding these shifts is not merely beneficial but essential for survival and growth. As we approach January 2026, a significant event looms on the horizon: an anticipated interest rate hike. This isn’t just another economic adjustment; it’s a pivotal moment that could profoundly reshape the operational realities, financial health, and strategic outlook for countless small enterprises across various sectors. The focus of this special investigation is to delve deep into the unforeseen impact of this January 2026 interest rate hike on small businesses, examining the multifaceted challenges and opportunities it presents.
For many small businesses, access to capital, managing debt, and predicting consumer spending are foundational pillars. An increase in interest rates directly affects these pillars, creating ripple effects that can be both immediate and long-lasting. While larger corporations often have the financial buffers and diverse portfolios to absorb such shocks, small businesses, with their often tighter margins and greater reliance on credit, are particularly vulnerable. This article aims to provide a comprehensive analysis, moving beyond surface-level predictions to explore the nuanced ways in which this economic shift will manifest.
We will dissect the mechanisms through which an interest rate hike small business operations, from the cost of borrowing to consumer demand. Furthermore, we will explore the less obvious, ‘unforeseen’ consequences that often catch businesses off guard, such as shifts in supplier relationships, employee retention challenges, and the psychological impact on entrepreneur confidence. Our goal is to equip small business owners with the knowledge and foresight necessary to not only weather the impending changes but to strategically adapt and even thrive in the new economic environment. This requires a proactive approach, a willingness to reassess existing models, and an embrace of innovative solutions.
Anúncios
Understanding the January 2026 Interest Rate Hike: What It Means
Before we can fully grasp the impact, it’s crucial to understand the nature and implications of an interest rate hike itself. Central banks typically raise interest rates as a tool to combat inflation, cool down an overheating economy, or stabilize currency. By making borrowing more expensive, they aim to reduce spending, curb demand, and ultimately slow down price increases. However, this macro-economic strategy has direct micro-economic consequences, especially for the bedrock of many economies: small businesses.
The January 2026 hike is anticipated to be a response to prevailing economic conditions, potentially including persistent inflationary pressures or robust economic growth that policymakers deem unsustainable. The specific percentage increase will dictate the severity of its effects, but even a modest rise can trigger significant adjustments. For small businesses, this translates to higher costs for loans, lines of credit, and mortgages. It affects everything from purchasing inventory and upgrading equipment to financing expansion plans and managing operational cash flow.
The announcement and subsequent implementation of such a hike often send ripples through financial markets, influencing investor confidence and consumer behavior. Businesses that rely on consumer credit, for example, might see a downturn in sales as borrowing becomes less attractive for their customers. Similarly, businesses with variable-rate loans will experience an immediate increase in their debt servicing costs, directly impacting their bottom line. Understanding these fundamental mechanics is the first step in preparing for the challenges ahead and formulating effective strategies to mitigate the adverse effects of an interest rate hike small business operations will undoubtedly face.
Direct Financial Impacts: The Immediate Squeeze
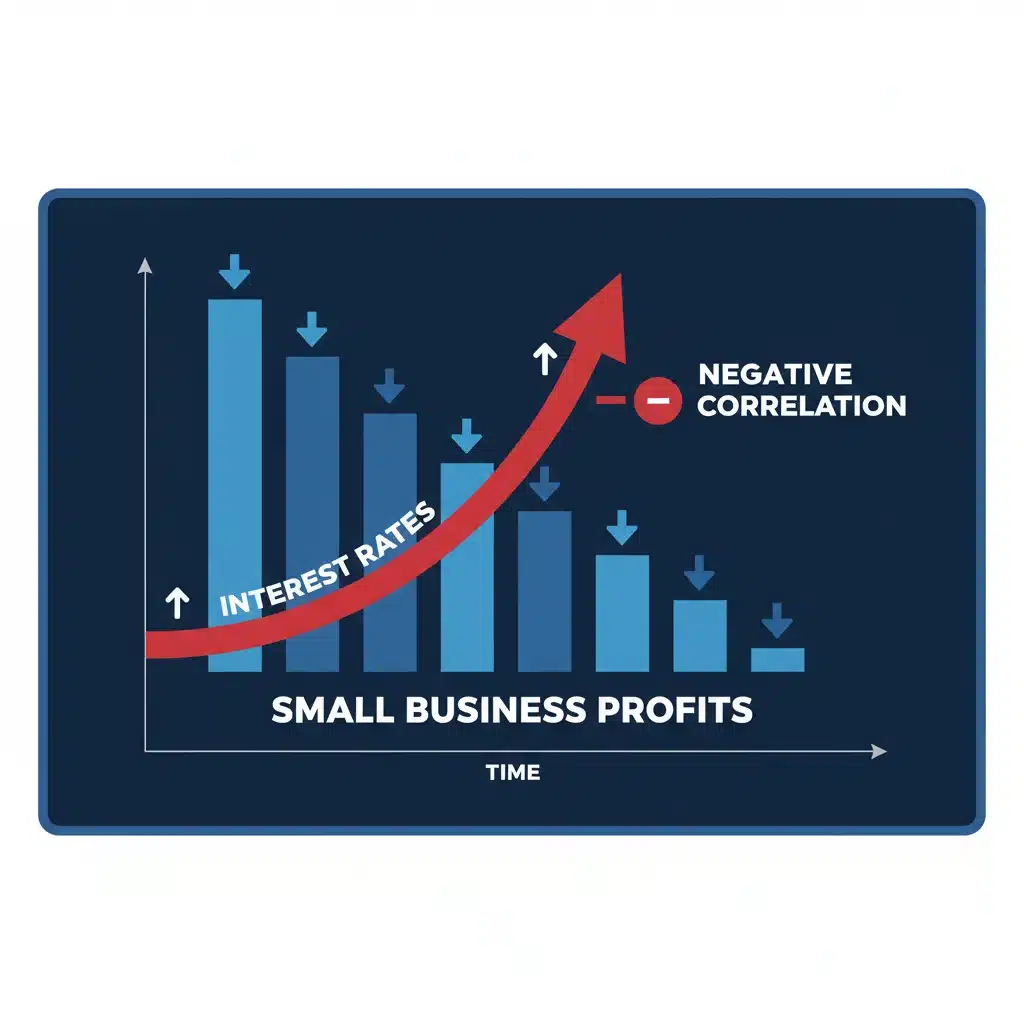
The most immediate and discernible impact of an interest rate hike small business entities will experience is financial. This isn’t just about higher loan repayments; it’s a cascade of financial pressures that can quickly erode profitability and liquidity.
Anúncios
Increased Cost of Borrowing
For small businesses that rely on loans for working capital, expansion, or inventory, an interest rate hike means a direct increase in their borrowing costs. Existing variable-rate loans will see immediate payment increases, squeezing cash flow. New loans or refinancing efforts will come with higher interest charges, making debt a more expensive proposition. This can deter investment in new projects, slow down growth, and even make it harder to cover day-to-day operational expenses.
Reduced Access to Credit
Beyond the increased cost, higher interest rates can lead to a tightening of credit markets. Lenders may become more risk-averse, increasing their lending standards and making it harder for small businesses, especially those with less established credit histories or perceived higher risk, to secure financing. This reduced access to credit can stifle innovation and prevent businesses from seizing growth opportunities.
Impact on Consumer Spending and Demand
Higher interest rates don’t just affect businesses; they impact consumers too. Mortgage payments can rise, credit card interest increases, and the cost of financing big-ticket items becomes more prohibitive. This often leads to a reduction in discretionary spending, directly impacting small businesses that cater to consumer markets. Retailers, hospitality venues, and service providers might experience a noticeable downturn in demand, forcing them to adjust pricing, inventory, and staffing levels.
Valuation and Investment Challenges
For small businesses looking to attract investment or considering an exit strategy, higher interest rates can depress valuations. Investors typically seek higher returns in a high-interest rate environment, making businesses with lower projected returns less attractive. This can complicate fundraising efforts and impact the long-term strategic planning of business owners.
Unforeseen Operational Challenges: Beyond the Balance Sheet
While the financial impacts are often the first to be discussed, the January 2026 interest rate hike small business owners face extends far beyond the balance sheet. There are several unforeseen operational challenges that can significantly disrupt day-to-day activities and long-term viability.
Supply Chain Disruptions and Increased Costs
An interest rate hike can ripple through global supply chains. Suppliers, facing their own increased borrowing costs, might pass these on to small businesses in the form of higher prices for raw materials or finished goods. Furthermore, if economic slowdowns occur in other regions due to similar monetary policies, it could lead to further supply chain bottlenecks and delays, impacting production schedules and customer satisfaction. Small businesses need to reassess their supplier relationships and potentially diversify their sourcing to mitigate these risks.
Talent Acquisition and Retention Difficulties
In a period of economic uncertainty and higher living costs (partially driven by higher interest rates impacting housing and credit), attracting and retaining talent becomes more challenging. Employees may demand higher wages to offset increased expenses, putting pressure on already tight payrolls. Small businesses, often unable to compete with larger corporations on salary and benefits, might struggle to maintain a skilled workforce. This can lead to decreased productivity, increased training costs, and a loss of institutional knowledge.
Innovation Stifling
Innovation often requires investment – in research and development, new technologies, or market testing. When the cost of capital rises and credit access tightens, small businesses may be forced to cut back on these crucial investments. This can stifle innovation, making it harder for them to adapt to changing market demands, compete with larger, more agile players, or develop new revenue streams. The long-term consequence could be a loss of competitive edge and reduced growth potential.
Increased Administrative Burden and Compliance Costs
Navigating a more complex financial environment often entails increased administrative work. Businesses may need to spend more time negotiating with lenders, re-evaluating financial models, and ensuring compliance with any new regulations that might emerge in response to the economic shifts. This converts valuable time and resources away from core business activities, adding an unseen cost to operations.
Strategic Adaptations: Building Resilience in the Face of Rising Rates
Understanding the challenges is only half the battle; the other half involves developing robust strategies to adapt. Small businesses are known for their agility and resilience, and these qualities will be paramount in navigating the post-January 2026 economic climate. Here are key strategic adaptations to consider:
Aggressive Debt Management and Refinancing
One of the most critical steps is to review all existing debt. Businesses with variable-rate loans should explore options for refinancing into fixed-rate loans before the hike takes full effect, if feasible. Prioritizing the repayment of high-interest debt can significantly reduce future financial strain. Developing a stringent debt management plan is essential to free up cash flow for other operational needs. This proactive approach to debt can insulate a small business from the direct sting of an interest rate hike small business budgets will feel.
Optimizing Cash Flow and Reserves
Cash is king, especially in uncertain economic times. Small businesses should focus on optimizing their cash flow by improving accounts receivable processes, negotiating better payment terms with suppliers, and implementing stricter inventory management to reduce holding costs. Building a healthy cash reserve will provide a crucial buffer against unexpected expenses or periods of reduced revenue, offering financial stability when credit access might be constrained.
Diversification of Revenue Streams and Customer Base
Over-reliance on a single product, service, or customer segment can be risky. Diversifying revenue streams can provide stability if one area is particularly affected by reduced consumer spending. Exploring new markets, developing complementary products, or offering subscription-based services can create multiple income sources. Similarly, broadening the customer base reduces dependence on a few key clients, making the business more resilient to individual client downturns.
Cost-Cutting and Efficiency Improvements
A thorough review of all operational costs is vital. This isn’t just about slashing expenses indiscriminately but identifying areas where efficiencies can be improved. This could involve adopting new technologies to automate processes, renegotiating contracts with vendors, optimizing energy consumption, or re-evaluating marketing spend for maximum ROI. Every dollar saved on operational costs contributes directly to the bottom line, helping to offset the impact of higher interest rates.
Embracing Digital Transformation and Technology
Technology can be a powerful ally in mitigating the effects of an interest rate hike. Cloud-based solutions can reduce IT infrastructure costs, while automation tools can improve efficiency and reduce labor costs. E-commerce platforms can open up new markets and reduce reliance on brick-and-mortar overheads. Investing strategically in digital transformation can lead to long-term cost savings, improved customer engagement, and enhanced operational agility.
Navigating the Human Element: Employees and Entrepreneurial Spirit
Beyond the financial and operational aspects, the January 2026 interest rate hike small business entities will experience also has a profound human dimension. It impacts employees, owners, and the very culture of the organization.
Employee Engagement and Retention Strategies
As discussed, retaining talent can become challenging. Small businesses need to focus on non-monetary benefits, fostering a positive work environment, offering professional development opportunities, and promoting work-life balance. Open communication about the economic climate and the company’s strategies can build trust and loyalty, encouraging employees to stay and contribute to overcoming challenges. Creative solutions for employee support, such as financial literacy workshops, can also be beneficial.
Maintaining Entrepreneurial Confidence and Mental Well-being
Economic uncertainty can take a significant toll on the mental well-being of small business owners. The pressure to navigate these changes, make difficult decisions, and ensure the survival of their business can be immense. It’s crucial for entrepreneurs to prioritize their mental health, seek support from peer networks, mentors, or professional counselors, and celebrate small victories. Maintaining a positive, resilient entrepreneurial spirit is contagious and can inspire the entire team to push through adversity.
Community and Network Support
Small businesses often thrive within strong local and professional communities. Leveraging these networks for shared resources, collaborative marketing efforts, or mutual support can be invaluable. Industry associations, local chambers of commerce, and online forums can provide platforms for sharing insights, best practices, and even collective bargaining power with suppliers or service providers. The adage ‘strength in numbers’ holds particularly true during economic shifts.
Long-Term Outlook and Future Preparedness
The January 2026 interest rate hike is not an isolated event but a part of a larger economic cycle. For small businesses, the lessons learned and strategies implemented now will contribute to their long-term resilience and adaptability. This period should be viewed as an opportunity to stress-test business models, identify vulnerabilities, and build a more robust, future-proof enterprise.
Continuous Monitoring and Agility
The economic environment is dynamic. Small businesses must establish mechanisms for continuous monitoring of economic indicators, market trends, and competitor activities. Being agile enough to quickly adjust strategies, pivot business models, and seize new opportunities will be a defining characteristic of successful enterprises in the post-hike era. This includes regularly reviewing financial forecasts, market demand, and operational efficiencies.
Investing in Long-Term Value
While cost-cutting is important, it should not come at the expense of long-term value creation. Strategic investments in technology, employee training, brand building, and customer relationships will pay dividends in the future. These investments should be carefully evaluated for their potential ROI and aligned with the business’s core mission and values. A short-sighted focus on immediate savings can undermine future growth potential.
Advocacy and Policy Engagement
Small businesses often have a collective voice that can influence policy. Engaging with local and national business associations, and advocating for policies that support small enterprise growth, can help shape a more favorable operating environment. This includes advocating for access to affordable credit, tax incentives, and programs that foster innovation and job creation. Understanding how an interest rate hike small business prosperity can be mitigated through policy is key.
Conclusion: Navigating the New Economic Reality
The anticipated January 2026 interest rate hike represents a significant inflection point for small businesses. While it undoubtedly brings a wave of challenges, from increased borrowing costs and tighter credit to shifts in consumer behavior and operational pressures, it also serves as a catalyst for innovation, efficiency, and strategic re-evaluation. The unforeseen impacts, often more subtle than the direct financial hit, demand a holistic and proactive approach to business management.
By focusing on aggressive debt management, optimizing cash flow, diversifying revenue streams, and embracing technological advancements, small businesses can build the resilience needed to navigate this new economic reality. Furthermore, prioritizing employee well-being, fostering a strong entrepreneurial spirit, and leveraging community support will be crucial for maintaining morale and collective strength.
The future is not about passively reacting to economic shifts but about actively shaping a business’s response. Those small businesses that demonstrate foresight, adaptability, and a commitment to continuous improvement will not only survive the impact of the January 2026 interest rate hike but will likely emerge stronger, more efficient, and better positioned for sustained success in the evolving global economy. This period calls for strategic thinking, prudent financial management, and an unwavering commitment to the core values that define small business entrepreneurship.