Maximizing Your 401(k) Contributions in 2026: Boost Retirement Savings
Anúncios
Retirement planning is a marathon, not a sprint, and for many, the 401(k) stands as a cornerstone of that long-term financial strategy. As we look ahead to 2026, understanding and maximizing your 401k contributions 2026 becomes paramount. It’s not just about setting aside money; it’s about optimizing every dollar to ensure a comfortable and secure future. This comprehensive guide will delve into the projected limits, strategic approaches, and often-overlooked opportunities to supercharge your retirement savings.
The landscape of retirement savings is constantly evolving, with inflation and economic shifts influencing contribution limits and investment strategies. Staying informed and proactive is key. By strategically increasing your 401k contributions 2026, you’re not just saving more; you’re leveraging tax advantages, potential employer matches, and the incredible power of compound interest to build a robust financial future.
Understanding the 401(k) Landscape for 2026
Before diving into specific strategies, it’s crucial to grasp the foundational elements of 401(k) plans and how they are expected to operate in 2026. While official limits for 2026 are typically announced later in the preceding year, we can make informed projections based on historical trends and current economic indicators. The Internal Revenue Service (IRS) adjusts these limits annually, primarily to account for inflation, ensuring that the purchasing power of your retirement savings is maintained.
Anúncios
A 401(k) is an employer-sponsored retirement plan that allows employees to save and invest for retirement on a tax-deferred basis. This means that contributions and earnings grow tax-free until retirement, when withdrawals are taxed as ordinary income. Some plans also offer a Roth 401(k) option, where contributions are made with after-tax dollars, but qualified withdrawals in retirement are entirely tax-free. Understanding the distinction between traditional and Roth 401(k)s is the first step in tailoring your contribution strategy.
The primary benefit of a 401(k) lies in its tax advantages. Traditional 401(k) contributions reduce your taxable income in the year they are made, potentially lowering your current tax bill. Roth 401(k)s, while not offering an upfront tax deduction, provide tax-free income in retirement, which can be immensely valuable if you anticipate being in a higher tax bracket later in life. The choice often depends on your current income, projected future income, and overall tax strategy.
Projected 401(k) Contribution Limits for 2026
While the definitive numbers for 2026 are not yet released, we can anticipate the general direction. Historically, the IRS has increased the elective deferral limit (the amount you can contribute from your pay) and the catch-up contribution limit (for those aged 50 and over) to keep pace with inflation. For instance, the elective deferral limit has seen consistent increases over the years, reflecting economic growth and inflation. Similarly, the catch-up contribution limit has also been adjusted, acknowledging the need for older workers to accelerate their savings.
For 2026, it is reasonable to project a slight increase from previous years. Assuming an average inflation rate, the elective deferral limit for employees could potentially be in the range of $24,000 to $25,000. For those aged 50 and over, the catch-up contribution limit might see an increase to around $8,000 to $8,500. These are projections, and it is crucial to consult official IRS announcements closer to the end of 2025 for the precise figures. However, planning with these estimates in mind allows you to start strategizing your 401k contributions 2026 early.
Anúncios
Beyond individual contributions, there’s also the overall limit on contributions to a defined contribution plan, which includes both employee and employer contributions. This limit is significantly higher and also subject to annual adjustments. Understanding all these limits is essential for a holistic approach to maximizing your retirement savings.
Strategic Approaches to Maximize Your 401(k) in 2026
Maximizing your 401k contributions 2026 involves more than just contributing the maximum allowable amount. It requires a strategic approach that considers your personal financial situation, your employer’s plan features, and your long-term retirement goals. Here are several key strategies to consider:
1. Contribute at Least Enough to Get the Full Employer Match
This is arguably the most critical and often cited piece of advice in 401(k) planning. Many employers offer a matching contribution, effectively providing free money towards your retirement. For example, an employer might match 50 cents on the dollar for the first 6% of your salary you contribute. If you don’t contribute at least 6%, you’re leaving free money on the table – a guaranteed return on investment that is hard to beat.
Make it your absolute priority to contribute at least the percentage required to receive the full employer match. This should be the baseline for your 401k contributions 2026. If you’re not doing this, you’re missing out on a significant boost to your retirement savings that requires no additional effort beyond setting up the contribution.
2. Front-Load Your Contributions (If Possible)
Some financial experts advocate for front-loading your 401(k) contributions, especially if your employer’s matching formula allows for it and you have the financial capacity. This means contributing a larger percentage of your salary earlier in the year to reach the annual maximum sooner. The benefit of this strategy is that your money has more time in the market to grow through compounding. The earlier your money is invested, the longer it has to benefit from market returns.
However, be cautious about front-loading if your employer’s match is calculated per pay period and you stop contributing once you hit the maximum. Some plans have a ‘true-up’ provision that ensures you receive the full match regardless of when you contribute, while others do not. Always check with your HR department or plan administrator to understand how your employer’s matching contributions are calculated.
3. Increase Contributions Annually, Even by a Small Amount
Even if you can’t immediately max out your 401k contributions 2026, commit to increasing your contribution rate by at least 1% or 2% each year, especially when you receive a raise. This seemingly small adjustment can have a dramatic impact over the long term, thanks to the power of compound interest and the fact that you’re unlikely to miss a small percentage increase from your pay.
Many 401(k) plans offer an automatic escalation feature, allowing you to set a predefined increase in your contribution rate each year. Enrolling in this feature is a hands-off way to ensure your savings continue to grow without requiring you to manually adjust it each year. This systematic approach makes it easier to gradually reach the maximum contribution limits.
4. Utilize Catch-Up Contributions if You’re 50 or Older
If you are aged 50 or older by the end of 2026, you are eligible to make additional ‘catch-up’ contributions to your 401(k). As mentioned, these limits are separate from the standard elective deferral limit and are designed to help older workers boost their retirement savings as they approach retirement. This is a powerful tool for those who started saving later in life or who want to significantly accelerate their nest egg in their prime earning years.
For example, if the standard limit is $24,000 and the catch-up limit is $8,000, an individual aged 50 or over could contribute a total of $32,000 to their 401(k) in 2026. This extra contribution can make a substantial difference in retirement readiness, especially when combined with the potential for employer matching on these additional contributions (if your plan allows).
Advanced Strategies for Your 401(k) in 2026
Beyond the fundamental strategies, there are more advanced tactics you can employ to further enhance your 401k contributions 2026 and overall retirement planning.
1. Understand Your Investment Options and Diversification
While maximizing contributions is crucial, how your money is invested within the 401(k) is equally important. Most 401(k) plans offer a range of investment options, including target-date funds, index funds, mutual funds, and sometimes individual stocks or bonds. It’s vital to understand these options and choose investments that align with your risk tolerance, time horizon, and financial goals.
Diversification is key to managing risk. Don’t put all your eggs in one basket. A well-diversified portfolio typically includes a mix of equities (stocks) for growth and fixed income (bonds) for stability. As you get closer to retirement, you might gradually shift towards a more conservative allocation. Regularly review your portfolio’s performance and rebalance as needed to maintain your desired asset allocation.
2. Consider a Roth 401(k) Option
If your employer offers a Roth 401(k) option, it’s worth considering, especially if you anticipate being in a higher tax bracket in retirement than you are now. Contributions to a Roth 401(k) are made with after-tax dollars, meaning they don’t reduce your current taxable income. However, qualified withdrawals in retirement are completely tax-free, including all earnings. This can be a significant advantage, particularly for younger workers who have many years for their investments to grow tax-free.
The decision between a traditional and Roth 401(k) often comes down to your current versus future tax bracket expectations. If you expect your income to rise significantly, or if tax rates are projected to increase in the future, a Roth 401(k) could be a powerful tool for tax-free retirement income. You can even combine both options if your plan allows, contributing to both a traditional and Roth 401(k) within the annual limits.
3. The Mega Backdoor Roth Strategy (If Applicable)
For high-income earners who have already maxed out their traditional or Roth 401(k) elective deferrals and any available employer match, the ‘Mega Backdoor Roth’ strategy can be an advanced way to contribute even more to a Roth account. This strategy involves making after-tax non-Roth contributions to your 401(k) (if your plan allows it), and then converting those after-tax contributions to a Roth account (either Roth 401(k) or Roth IRA).
This strategy leverages the overall 401(k) contribution limit, which includes employee contributions, employer contributions, and after-tax employee contributions. For 2026, this overall limit could be in the range of $69,000 to $70,000 (plus catch-up contributions for those 50+). The difference between this overall limit and your combined employee/employer contributions can potentially be contributed as after-tax dollars and then converted to Roth. This strategy is complex and requires your 401(k) plan to specifically allow after-tax contributions and in-service distributions or Roth conversions. Always consult with a financial advisor and your plan administrator to determine if this is an option for you.
4. Review Your Beneficiary Designations
While not directly related to contributions, regularly reviewing your beneficiary designations for your 401(k) is a crucial part of comprehensive retirement planning. Life events such as marriage, divorce, birth of children, or death of a loved one can necessitate updates to your beneficiaries. Ensuring your beneficiaries are up-to-date ensures that your retirement assets will be distributed according to your wishes and can help avoid potential legal complications.
It’s also important to understand the implications of different beneficiary types (e.g., spouse vs. non-spouse) and the rules regarding inherited 401(k)s, as these have changed with the SECURE Act. A financial advisor can help you navigate these complexities.
Overcoming Obstacles to Maximizing Your 401(k)
Even with the best intentions, several obstacles can prevent individuals from maximizing their 401k contributions 2026. Recognizing and addressing these challenges is essential for successful retirement planning.
1. Competing Financial Priorities
For many, balancing retirement savings with other financial goals, such as paying off student loans, saving for a down payment on a house, or raising a family, can be challenging. It’s important to create a comprehensive budget and financial plan that prioritizes these goals. While other goals are important, remember that retirement savings benefit most from early and consistent contributions due to compound interest. Consider automating your 401(k) contributions to ensure you’re consistently saving before other expenses arise.
2. Lack of Financial Literacy
The world of retirement planning can seem daunting, filled with jargon and complex rules. A lack of understanding about how 401(k)s work, the benefits they offer, or how to choose appropriate investments can deter people from maximizing their contributions. Take the time to educate yourself through reputable financial resources, workshops, or by consulting with a financial advisor. Many employers also offer educational resources as part of their 401(k) plan.
3. Perceived Lack of Funds
Some individuals believe they don’t earn enough to maximize their 401(k) contributions. While it’s true that not everyone can contribute the maximum, even small increases can make a significant difference over time. As discussed, aim to at least get the employer match, and then commit to increasing your contributions by 1% or 2% each year, especially after a raise. You might be surprised at how quickly your savings grow.
Review your budget for areas where you can cut back, even temporarily, to free up funds for your 401(k). Small sacrifices now can lead to substantial gains in retirement.
The Power of Compound Interest and Time
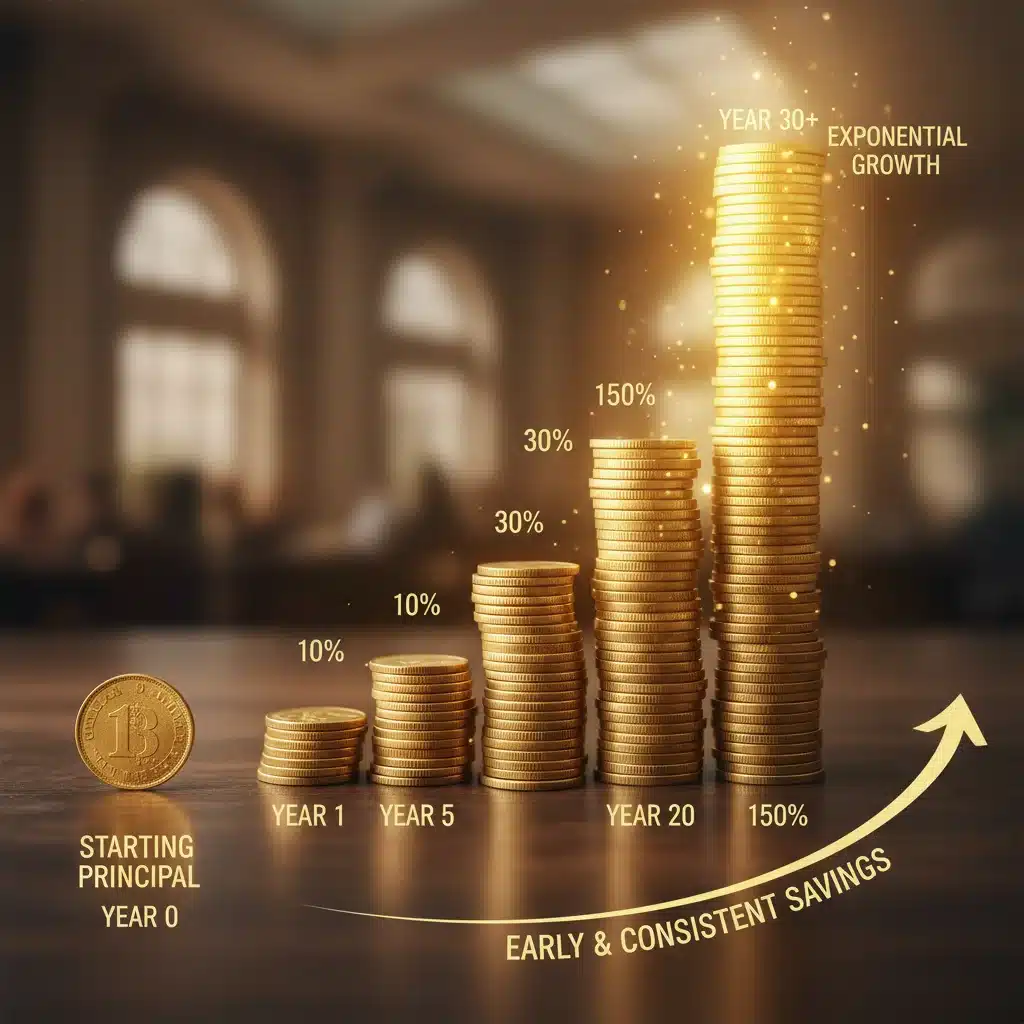
The single most powerful ally in your quest to maximize your 401k contributions 2026 is compound interest. This phenomenon allows your earnings to generate their own earnings, creating an exponential growth effect. The earlier you start contributing and the more consistently you contribute, the greater the impact of compounding.
Consider two individuals: one starts saving $500 per month at age 25, and another starts saving $700 per month at age 35. Assuming an average annual return of 7%, the person who started at 25 will likely have significantly more money by retirement age, even though they contributed less per month and less overall. This illustrates why maximizing your 401k contributions 2026 now, regardless of your age, is so crucial.
Time in the market, not timing the market, is what truly matters. By consistently contributing and investing for the long term, you give your money the opportunity to ride out market fluctuations and benefit from sustained growth over decades. This long-term perspective is fundamental to successful 401(k) planning.
Integrating Your 401(k) with Overall Financial Planning
Your 401(k) is a vital component, but it’s just one piece of your overall financial puzzle. For truly effective financial planning, your 401k contributions 2026 strategy should be integrated with other aspects of your financial life:
- Emergency Fund: Before aggressively saving for retirement, ensure you have a robust emergency fund (typically 3-6 months of living expenses) in an easily accessible, liquid account. This prevents you from having to tap into your 401(k) early, incurring penalties and taxes.
- Debt Management: High-interest debt (like credit card debt) can erode your financial progress. Prioritize paying off such debt while still contributing enough to your 401(k) to get the employer match. Once high-interest debt is eliminated, you can redirect those payments towards increasing your 401(k) contributions.
- Other Retirement Accounts: Consider diversifying your retirement savings across different account types, such as IRAs (Traditional or Roth), HSAs (Health Savings Accounts) which offer triple tax advantages, or taxable brokerage accounts. This diversification can provide flexibility and additional tax benefits.
- Estate Planning: As mentioned earlier, reviewing beneficiaries is part of estate planning. But also consider how your 401(k) fits into your broader estate plan, especially if you have a large balance or complex family situation.
- Financial Advisor: For complex financial situations or if you simply prefer professional guidance, working with a qualified financial advisor can be invaluable. They can help you create a personalized retirement plan, optimize your investment strategy, and navigate tax implications.
Conclusion: A Path to a Secure Retirement
Maximizing your 401k contributions 2026 is not merely an annual task; it’s a continuous commitment to your future self. By understanding the projected limits, leveraging employer matches, and employing strategic contribution methods, you can significantly enhance your retirement readiness. Whether you’re just starting your career or nearing retirement, there are actionable steps you can take to optimize your 401(k).
Remember the power of consistency, the magic of compound interest, and the importance of staying informed about IRS changes. Take advantage of every opportunity to save, invest wisely, and regularly review your plan. Your future financial security depends on the decisions you make today. Start planning now to make 2026 a landmark year for your retirement savings, paving the way for the comfortable and fulfilling retirement you envision.