Navigating 2026 Tax Code Changes: Maximizing Deductions
Anúncios
The landscape of taxation is in constant flux, and as we approach 2026, significant changes to the tax code are on the horizon. These adjustments will undoubtedly impact individuals, families, and businesses across the spectrum. Understanding these impending shifts is not just about compliance; it’s about strategic financial planning to ensure you’re maximizing every possible deduction and minimizing your tax liability. This comprehensive guide will delve into the intricacies of the upcoming 2026 tax code changes, offering five key strategies to help you navigate this evolving environment and optimize your financial health. Our focus is on empowering you with the knowledge to proactively adapt and thrive amidst these legislative updates, ensuring you are well-prepared to leverage every opportunity for 2026 Tax Deductions.
The current tax framework, largely shaped by the Tax Cuts and Jobs Act (TCJA) of 2017, is set to undergo substantial modifications. Many provisions from the TCJA are scheduled to expire or change at the end of 2025, paving the way for a new era of taxation in 2026. These expirations include, but are not limited to, individual income tax rates, the standard deduction amounts, certain itemized deduction limitations, and the estate tax exemption. For businesses, some immediate expensing provisions and limitations on business interest deductions may also see alterations. The sheer scope of these potential changes necessitates a proactive and informed approach to financial management. Ignoring these shifts could lead to missed opportunities for savings, while a well-thought-out strategy can unlock significant benefits, particularly in maximizing your 2026 Tax Deductions.
Anúncios
Preparing for these changes requires more than just a cursory glance at headlines. It demands a deep dive into how these modifications will specifically affect your income, investments, and overall financial situation. The goal is to move beyond mere reaction and instead cultivate a robust, forward-thinking strategy that anticipates the future tax environment. By understanding the core principles behind these changes and implementing smart financial practices, you can transform potential challenges into opportunities for growth and increased financial efficiency. Let’s explore the critical strategies that will guide you through the 2026 tax landscape.
Understanding the Sunset of TCJA Provisions and Its Impact on 2026 Tax Deductions
The Tax Cuts and Jobs Act (TCJA) of 2017 brought about some of the most significant changes to the U.S. tax code in decades. While many of its provisions were made permanent for corporations, a substantial number of individual income tax provisions were designed with an expiration date: December 31, 2025. This means that as of January 1, 2026, unless Congress acts to extend them, these provisions will "sunset," reverting to pre-TCJA law or being modified in new legislation. Understanding these specific sunsets is the cornerstone of preparing for optimal 2026 Tax Deductions.
One of the most impactful sunsets relates to individual income tax rates. Under the TCJA, tax rates were generally lowered across most income brackets. Without legislative intervention, these rates are expected to revert to the higher pre-TCJA levels. For instance, the 10%, 12%, 22%, 24%, 32%, 35%, and 37% rates could potentially return to 10%, 15%, 25%, 28%, 33%, 35%, and 39.6%. This shift will directly influence your net income and the value of any deductions you claim. A higher marginal tax rate often means that each dollar of deduction is more valuable, emphasizing the importance of maximizing every available write-off.
Another critical area is the standard deduction. The TCJA significantly increased the standard deduction amounts, leading many taxpayers to claim the standard deduction rather than itemizing. For 2026, these amounts are projected to decrease substantially if they revert to pre-TCJA levels, adjusted for inflation. This change could mean that more taxpayers find it beneficial to itemize their deductions once again. Consequently, diligent record-keeping of potential itemized deductions, such as state and local taxes (SALT), mortgage interest, and charitable contributions, becomes paramount. The "SALT cap" of $10,000, introduced by the TCJA, is also set to expire, which could provide significant relief for taxpayers in high-tax states, allowing for larger itemized deductions.
Furthermore, the qualified business income (QBI) deduction, or Section 199A deduction, which allows eligible pass-through entities to deduct up to 20% of their qualified business income, is also scheduled to sunset. This deduction has been a major tax benefit for many small business owners and self-employed individuals. Its expiration could lead to a significant increase in taxable income for these taxpayers, making other business-related deductions even more crucial. Understanding whether your business qualifies for other tax breaks and how to structure your operations to optimize them will be vital.
Anúncios
The estate and gift tax exemption amounts, which were temporarily doubled under the TCJA, are also set to revert to their pre-TCJA levels. This change has profound implications for high-net-worth individuals and families engaged in estate planning. Planning for wealth transfer and considering strategies like gifting or establishing trusts well before 2026 could be highly beneficial to take advantage of the higher exemption amounts while they last. The reduced exemption will mean that more estates could be subject to federal estate taxes, making careful planning indispensable.
Finally, several other less prominent but still impactful provisions are slated for change. These include the elimination of miscellaneous itemized deductions (e.g., unreimbursed employee expenses, tax preparation fees), the suspension of personal exemptions, and changes to various education credits and deductions. While individual impacts may vary, the cumulative effect of these sunsets creates a complex environment that demands a comprehensive review of your financial situation. Proactive engagement with these changes will be key to unlocking maximum 2026 Tax Deductions.
Strategy 1: Optimize Your Itemized Deductions (Revisit Itemizing)
With the potential reversion of the standard deduction to pre-TCJA levels, many taxpayers who previously opted for the higher standard deduction may find themselves in a position where itemizing becomes more advantageous. This makes a thorough review and optimization of your itemized deductions a critical strategy for maximizing your 2026 Tax Deductions.
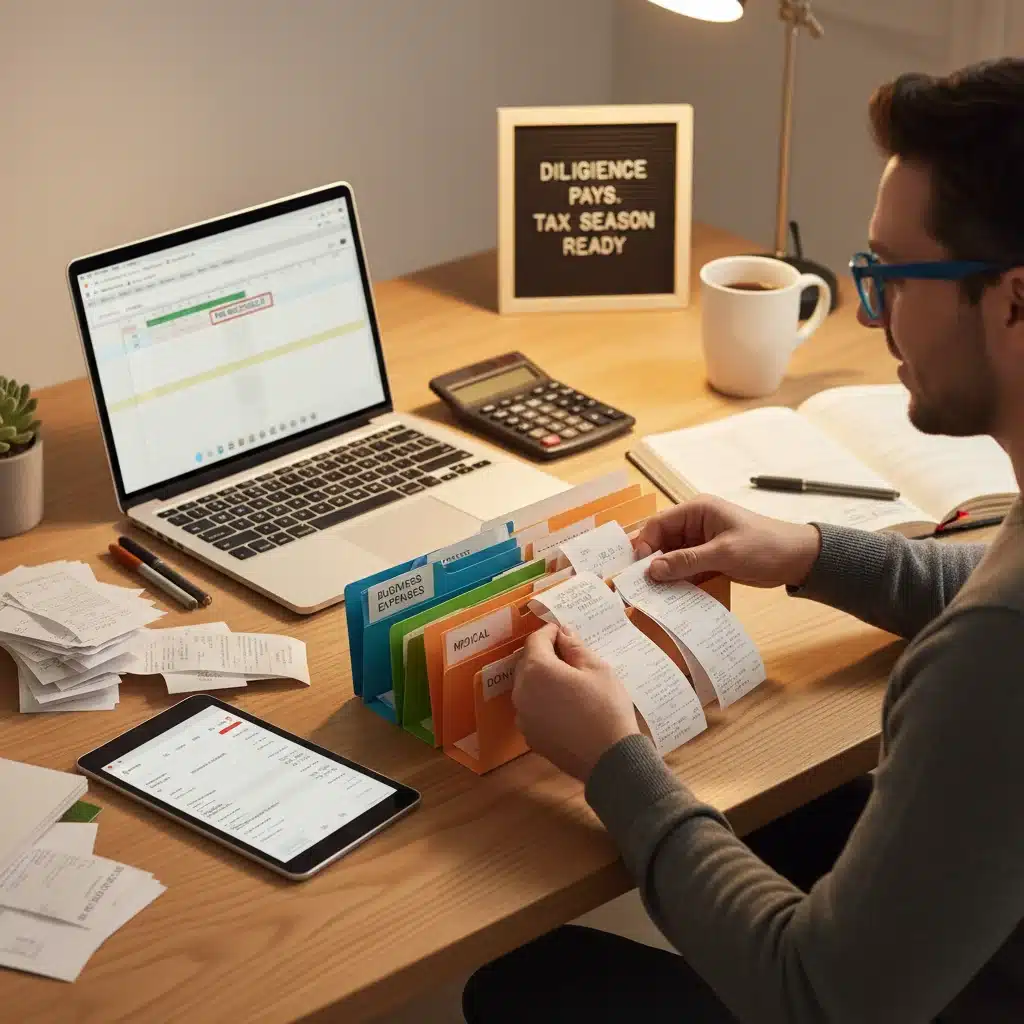
The first step is to meticulously track and categorize all potential itemized deductions throughout the year. This includes, but is not limited to, medical expenses, state and local taxes (SALT), home mortgage interest, charitable contributions, and certain investment interest expenses. Digital tools, spreadsheets, or even a dedicated folder for physical receipts can streamline this process. The key is to be proactive, not reactive, in your record-keeping.
One of the most significant changes could be to the State and Local Tax (SALT) deduction. The TCJA imposed a $10,000 cap on the amount of state and local income, sales, and property taxes that could be deducted. If this cap expires as scheduled, taxpayers in high-tax states could see a substantial increase in their itemized deductions. It’s important to understand your state’s tax structure and how this potential change could benefit you. For those living in states with high property taxes or income taxes, the removal of the SALT cap could be a game-changer.
Charitable contributions remain a powerful way to reduce taxable income. Consider "bunching" your charitable contributions. This strategy involves consolidating two or more years’ worth of donations into a single tax year to exceed the standard deduction threshold in that year, allowing you to itemize. In other years, you might take the standard deduction. For example, if you typically donate $5,000 annually, you might donate $10,000 in one year (representing two years’ worth) to increase your itemized deductions for that year. Donor-advised funds (DAFs) can be excellent tools for this strategy, allowing you to make a large, tax-deductible contribution to the DAF in one year and then recommend grants to charities over several years.
Mortgage interest deductions are another significant component for many homeowners. If you have a mortgage, ensure you are tracking all interest paid. The rules around mortgage interest deductions can be complex, especially with home equity debt. Understanding the distinctions between acquisition indebtedness (used to buy, build, or substantially improve a home) and home equity indebtedness (used for other purposes) is crucial. While the TCJA limited the deduction for interest on home equity debt, the expiration could potentially restore some of these deductions, depending on new legislation. Always consult IRS guidelines or a tax professional for the most accurate information regarding your specific mortgage interest deductions.
Medical expense deductions can also be substantial for individuals with significant healthcare costs. Generally, you can deduct the amount of medical expenses that exceeds 7.5% of your adjusted gross income (AGI). This threshold can be difficult to meet for many, but for those with chronic conditions, major surgeries, or extensive medical needs, it can provide significant tax relief. Keep detailed records of all medical and dental care costs, including insurance premiums, doctor visits, hospital stays, prescription medications, and even transportation to medical appointments. These can all contribute to reaching the AGI threshold for deduction.
Finally, consider miscellaneous itemized deductions that were suspended under the TCJA. These included unreimbursed employee expenses, tax preparation fees, and investment expenses. While their return is not guaranteed, monitoring any new legislation that might reinstate these or similar deductions is wise. The landscape of itemized deductions is set to become more dynamic, and a proactive, organized approach will be your best asset in maximizing your 2026 Tax Deductions through itemizing.
Strategy 2: Proactive Retirement and Investment Planning
Retirement and investment accounts offer some of the most powerful tools for tax deferral and reduction. As we look towards 2026, proactive planning in these areas becomes even more critical, especially with potential changes to tax rates. Maximizing contributions to tax-advantaged accounts is a cornerstone of effective tax strategy, directly impacting your 2026 Tax Deductions.
Traditional IRAs and 401(k)s allow you to contribute pre-tax dollars, reducing your current taxable income. The money grows tax-deferred until retirement, when withdrawals are taxed as ordinary income. If individual income tax rates are indeed set to increase in 2026, contributing more to these accounts in years leading up to 2026, or continuing to maximize contributions in 2026, could be particularly advantageous. Deductions taken at a higher marginal tax rate are more valuable, making these contributions a powerful tool for reducing your overall tax burden. Ensure you are contributing at least enough to get any employer match in your 401(k), as this is essentially free money and a significant boost to your retirement savings.
Conversely, Roth IRAs and Roth 401(k)s are funded with after-tax dollars, meaning contributions are not tax-deductible. However, qualified withdrawals in retirement are entirely tax-free. If you anticipate being in a higher tax bracket in retirement than you are now, or if you believe future tax rates will be higher than current ones, Roth accounts can be an excellent choice. The decision between traditional and Roth contributions often hinges on your expected future tax bracket versus your current one. With potential rate increases in 2026, evaluating this choice becomes even more pertinent. A "Roth conversion" – moving pre-tax money from a traditional IRA or 401(k) to a Roth account – could also be strategically timed. While conversions are taxable events, doing them in a year when your income is lower or before rates potentially increase could be beneficial.
Health Savings Accounts (HSAs) are often dubbed the "triple tax advantage" accounts. Contributions are tax-deductible (or pre-tax if made through payroll deductions), the money grows tax-free, and qualified withdrawals for medical expenses are also tax-free. HSAs are available to those with high-deductible health plans (HDHPs). Maximizing HSA contributions is an excellent way to save for future medical costs while reducing your current taxable income, making it a powerful tool for 2026 Tax Deductions. For those who can afford to pay current medical expenses out-of-pocket, letting HSA funds grow untouched can create a significant tax-free nest egg for retirement healthcare costs.
Beyond retirement accounts, consider tax-loss harvesting in your investment portfolio. This strategy involves selling investments at a loss to offset capital gains and, if losses exceed gains, up to $3,000 of ordinary income each year. Any remaining losses can be carried forward to future years. Tax-loss harvesting can be particularly effective in volatile markets, allowing you to rebalance your portfolio while generating valuable tax deductions. This must be done carefully to avoid the "wash sale" rule, which disallows a loss if you buy substantially identical securities within 30 days before or after the sale.
Finally, for those with significant wealth, estate planning strategies should be reviewed in light of the potential sunset of the increased estate and gift tax exemption. If the exemption reverts to lower levels, more estates could be subject to federal estate tax. Utilizing the higher exemption amounts while they are still in effect, through gifting or other wealth transfer strategies, could be a wise move. Consulting with a financial advisor specializing in estate planning is highly recommended to navigate these complex rules and optimize your long-term financial legacy.
Strategy 3: Business Tax Planning and Entity Structure Review
For business owners, the 2026 tax code changes present a critical juncture for reviewing entity structure and tax planning strategies. With the potential expiration of the Qualified Business Income (QBI) deduction and other business-related provisions, a proactive approach is essential to maximize your 2026 Tax Deductions and ensure your business remains tax-efficient.
The QBI deduction, which allows eligible pass-through entities (sole proprietorships, partnerships, S corporations) to deduct up to 20% of their qualified business income, has been a significant tax break for many. Its scheduled expiration means that businesses currently relying on this deduction could see a substantial increase in their taxable income. This makes it imperative to explore alternative strategies to mitigate this impact.
One crucial step is to review your business entity structure. The choice of entity – whether you operate as a sole proprietorship, partnership, S corporation, or C corporation – has profound tax implications. For example, C corporations are subject to corporate income tax rates, which were permanently lowered by the TCJA. If individual income tax rates increase significantly in 2026, while corporate rates remain stable, some businesses might find it advantageous to consider converting to a C corporation structure, depending on their specific circumstances and future growth plans. However, C corporations also face the issue of "double taxation" if profits are distributed as dividends, so a thorough analysis is needed.
For pass-through entities, even without the QBI deduction, there are still many ways to manage taxable income. Maximizing legitimate business expenses is always a priority. This includes everything from office supplies and utilities to employee salaries, marketing costs, and professional development. Ensure you have robust record-keeping systems to document all business expenditures. The IRS scrutinizes business deductions, so accurate and comprehensive documentation is key.
Consider accelerating deductions into 2025 where possible, especially if you anticipate higher tax rates in 2026. This might involve purchasing equipment or making other significant business investments before the end of 2025 to take advantage of current depreciation rules or expensing provisions. Conversely, deferring income into 2026 might be beneficial if you expect your business’s overall income to be lower in that year, or if new, more favorable tax provisions are enacted. This strategy requires careful forecasting and coordination with your tax advisor.
Employee benefits also offer avenues for tax savings. Providing tax-deductible benefits to employees, such as health insurance premiums, retirement plan contributions, and certain fringe benefits, can reduce your business’s taxable income while also attracting and retaining talent. For self-employed individuals, establishing a Solo 401(k) or SEP IRA allows for significant pre-tax contributions, reducing personal taxable income and building retirement wealth. These contributions are a direct deduction for the business owner, making them excellent for maximizing 2026 Tax Deductions.
Furthermore, stay informed about any new tax credits or incentives that may be introduced or extended by Congress. Tax policy is dynamic, and new legislation could emerge to address specific economic goals, such as promoting clean energy, research and development, or job creation. Being aware of these opportunities can provide additional avenues for tax savings. Engaging with a qualified tax professional or business accountant specializing in small business taxation is invaluable during this period of change. They can help you analyze your specific situation, model different scenarios, and recommend the most advantageous entity structure and tax strategies for your business in 2026 and beyond.
Strategy 4: Leverage Education and Family-Related Tax Benefits
The 2026 tax code changes will also impact various education and family-related tax benefits. Understanding and strategically utilizing these provisions can lead to significant savings for families, especially concerning college planning and dependent care. This strategy focuses on maximizing these specific 2026 Tax Deductions and credits.
For families saving for higher education, 529 plans remain a cornerstone of tax-advantaged savings. Contributions to a 529 plan grow tax-free, and qualified withdrawals for educational expenses (tuition, fees, room, board, books) are also tax-free at the federal level, and often at the state level as well. While contributions are not federally tax-deductible, many states offer a tax deduction or credit for contributions to their 529 plans. If tax rates increase in 2026, the tax-free growth and withdrawals become even more valuable, as you avoid paying higher taxes on investment gains. Consider "front-loading" 529 plan contributions – contributing up to five years’ worth of gift tax exclusion in a single year – to accelerate tax-free growth.
Education credits, such as the American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC), are crucial for offsetting college expenses. The AOTC provides a maximum annual credit of $2,500 per eligible student for the first four years of post-secondary education, with 40% of the credit being refundable. The LLC offers a maximum annual credit of $2,000 per tax return for undergraduate, graduate, and professional degree courses. While these credits have income limitations, they directly reduce your tax liability dollar for dollar, making them incredibly valuable. Monitor any proposed changes to these credits as part of the 2026 tax reforms, as their parameters could be adjusted.
For those with dependents, the Child Tax Credit (CTC) is a significant benefit. The TCJA temporarily increased the CTC to $2,000 per qualifying child, with a refundable portion of up to $1,400. This credit is also scheduled to revert to its pre-TCJA amount of $1,000 per child in 2026, with stricter refundability rules, unless Congress intervenes. Families should be aware of this potential reduction and plan accordingly. If your family relies on the CTC, understanding its future structure is essential for accurate financial forecasting. The Child and Dependent Care Credit, which helps offset expenses for childcare for working parents, also has income limitations and specific requirements. Ensure you are tracking all eligible expenses for this credit.
Dependent care Flexible Spending Accounts (FSAs) offered by employers can be another excellent way to save on childcare costs. Contributions to a dependent care FSA are made with pre-tax dollars, reducing your taxable income. You can then use these funds to pay for eligible childcare expenses. This effectively provides a tax deduction for childcare costs, making it a valuable tool for families. However, funds must be used within the plan year, or you risk forfeiting them, so careful planning is necessary.
Finally, for those supporting elderly parents or other adult dependents, exploring specific deductions or credits related to their care may be beneficial. While direct deductions for adult dependents are limited, some medical expenses paid on behalf of a dependent can be included in your itemized medical expense calculation, provided you meet the AGI threshold. Staying informed about any new or modified provisions related to family support will be key to maximizing your 2026 Tax Deductions and credits as family dynamics often play a significant role in tax planning.
Strategy 5: Consult a Tax Professional and Stay Informed
Navigating the impending 2026 tax code changes can be complex, and attempting to do it alone might mean missing out on valuable deductions or making costly errors. The most crucial strategy for anyone – individuals, families, or businesses – is to consult a qualified tax professional and commit to staying informed. This proactive approach ensures you’re always leveraging the best strategies for your specific situation and maximizing your 2026 Tax Deductions.
A knowledgeable tax advisor or Certified Public Accountant (CPA) brings expertise that goes beyond simply filling out forms. They can provide personalized advice tailored to your unique financial circumstances, helping you understand how the 2026 changes will specifically impact your income, investments, and business operations. They can help you identify deductions you might overlook, strategize on optimal timing for income and expenses, and ensure compliance with all new regulations. For instance, they can assist with complex calculations related to capital gains, alternative minimum tax (AMT), or the intricacies of business deductions that might be unclear to the average taxpayer.
Furthermore, a tax professional can help you develop a multi-year tax plan. This involves looking beyond just 2026 and anticipating how future legislative changes or your personal financial trajectory might influence your tax strategy. They can help you model different scenarios, such as the impact of a Roth conversion, the timing of a major asset sale, or the most tax-efficient way to fund a child’s education. This forward-looking perspective is invaluable in an environment of significant tax reform.
Staying informed is equally vital. Tax laws are not static; they are subject to ongoing debate, amendments, and interpretations. Relying solely on information from a year or two ago will leave you unprepared. Subscribe to reputable financial news sources, follow updates from the IRS, and regularly check in with your tax advisor. Many tax professionals offer newsletters, webinars, or blog posts to keep their clients abreast of the latest developments. Being proactive in seeking out information means you can adjust your strategies promptly as new details emerge.
For business owners, staying informed about industry-specific tax incentives or regulations is particularly important. A tax professional specializing in your industry can provide insights into unique deductions or credits that apply to your business. They can also help you understand the implications of different accounting methods or inventory valuation techniques under the new tax regime, ensuring your business structure remains optimized for tax efficiency.
Finally, don’t underestimate the importance of good record-keeping. Even the most skilled tax professional can only work with the information you provide. Maintaining organized and accurate records of income, expenses, investments, and other financial transactions throughout the year will not only streamline the tax preparation process but also ensure that you don’t miss any legitimate deductions. Digital tools for expense tracking, cloud storage for important documents, and regular financial reviews can all contribute to robust record-keeping practices.
By embracing these five strategies – optimizing itemized deductions, proactive retirement and investment planning, strategic business tax planning, leveraging education and family benefits, and consulting with a tax professional while staying informed – you can confidently navigate the 2026 tax code changes. These shifts, while potentially challenging, also present opportunities for savvy taxpayers to enhance their financial well-being and maximize their 2026 Tax Deductions. Proactivity, organization, and expert guidance will be your greatest assets in this evolving tax landscape.